The Global Branded Residence Survey 2026: expanding into new territories
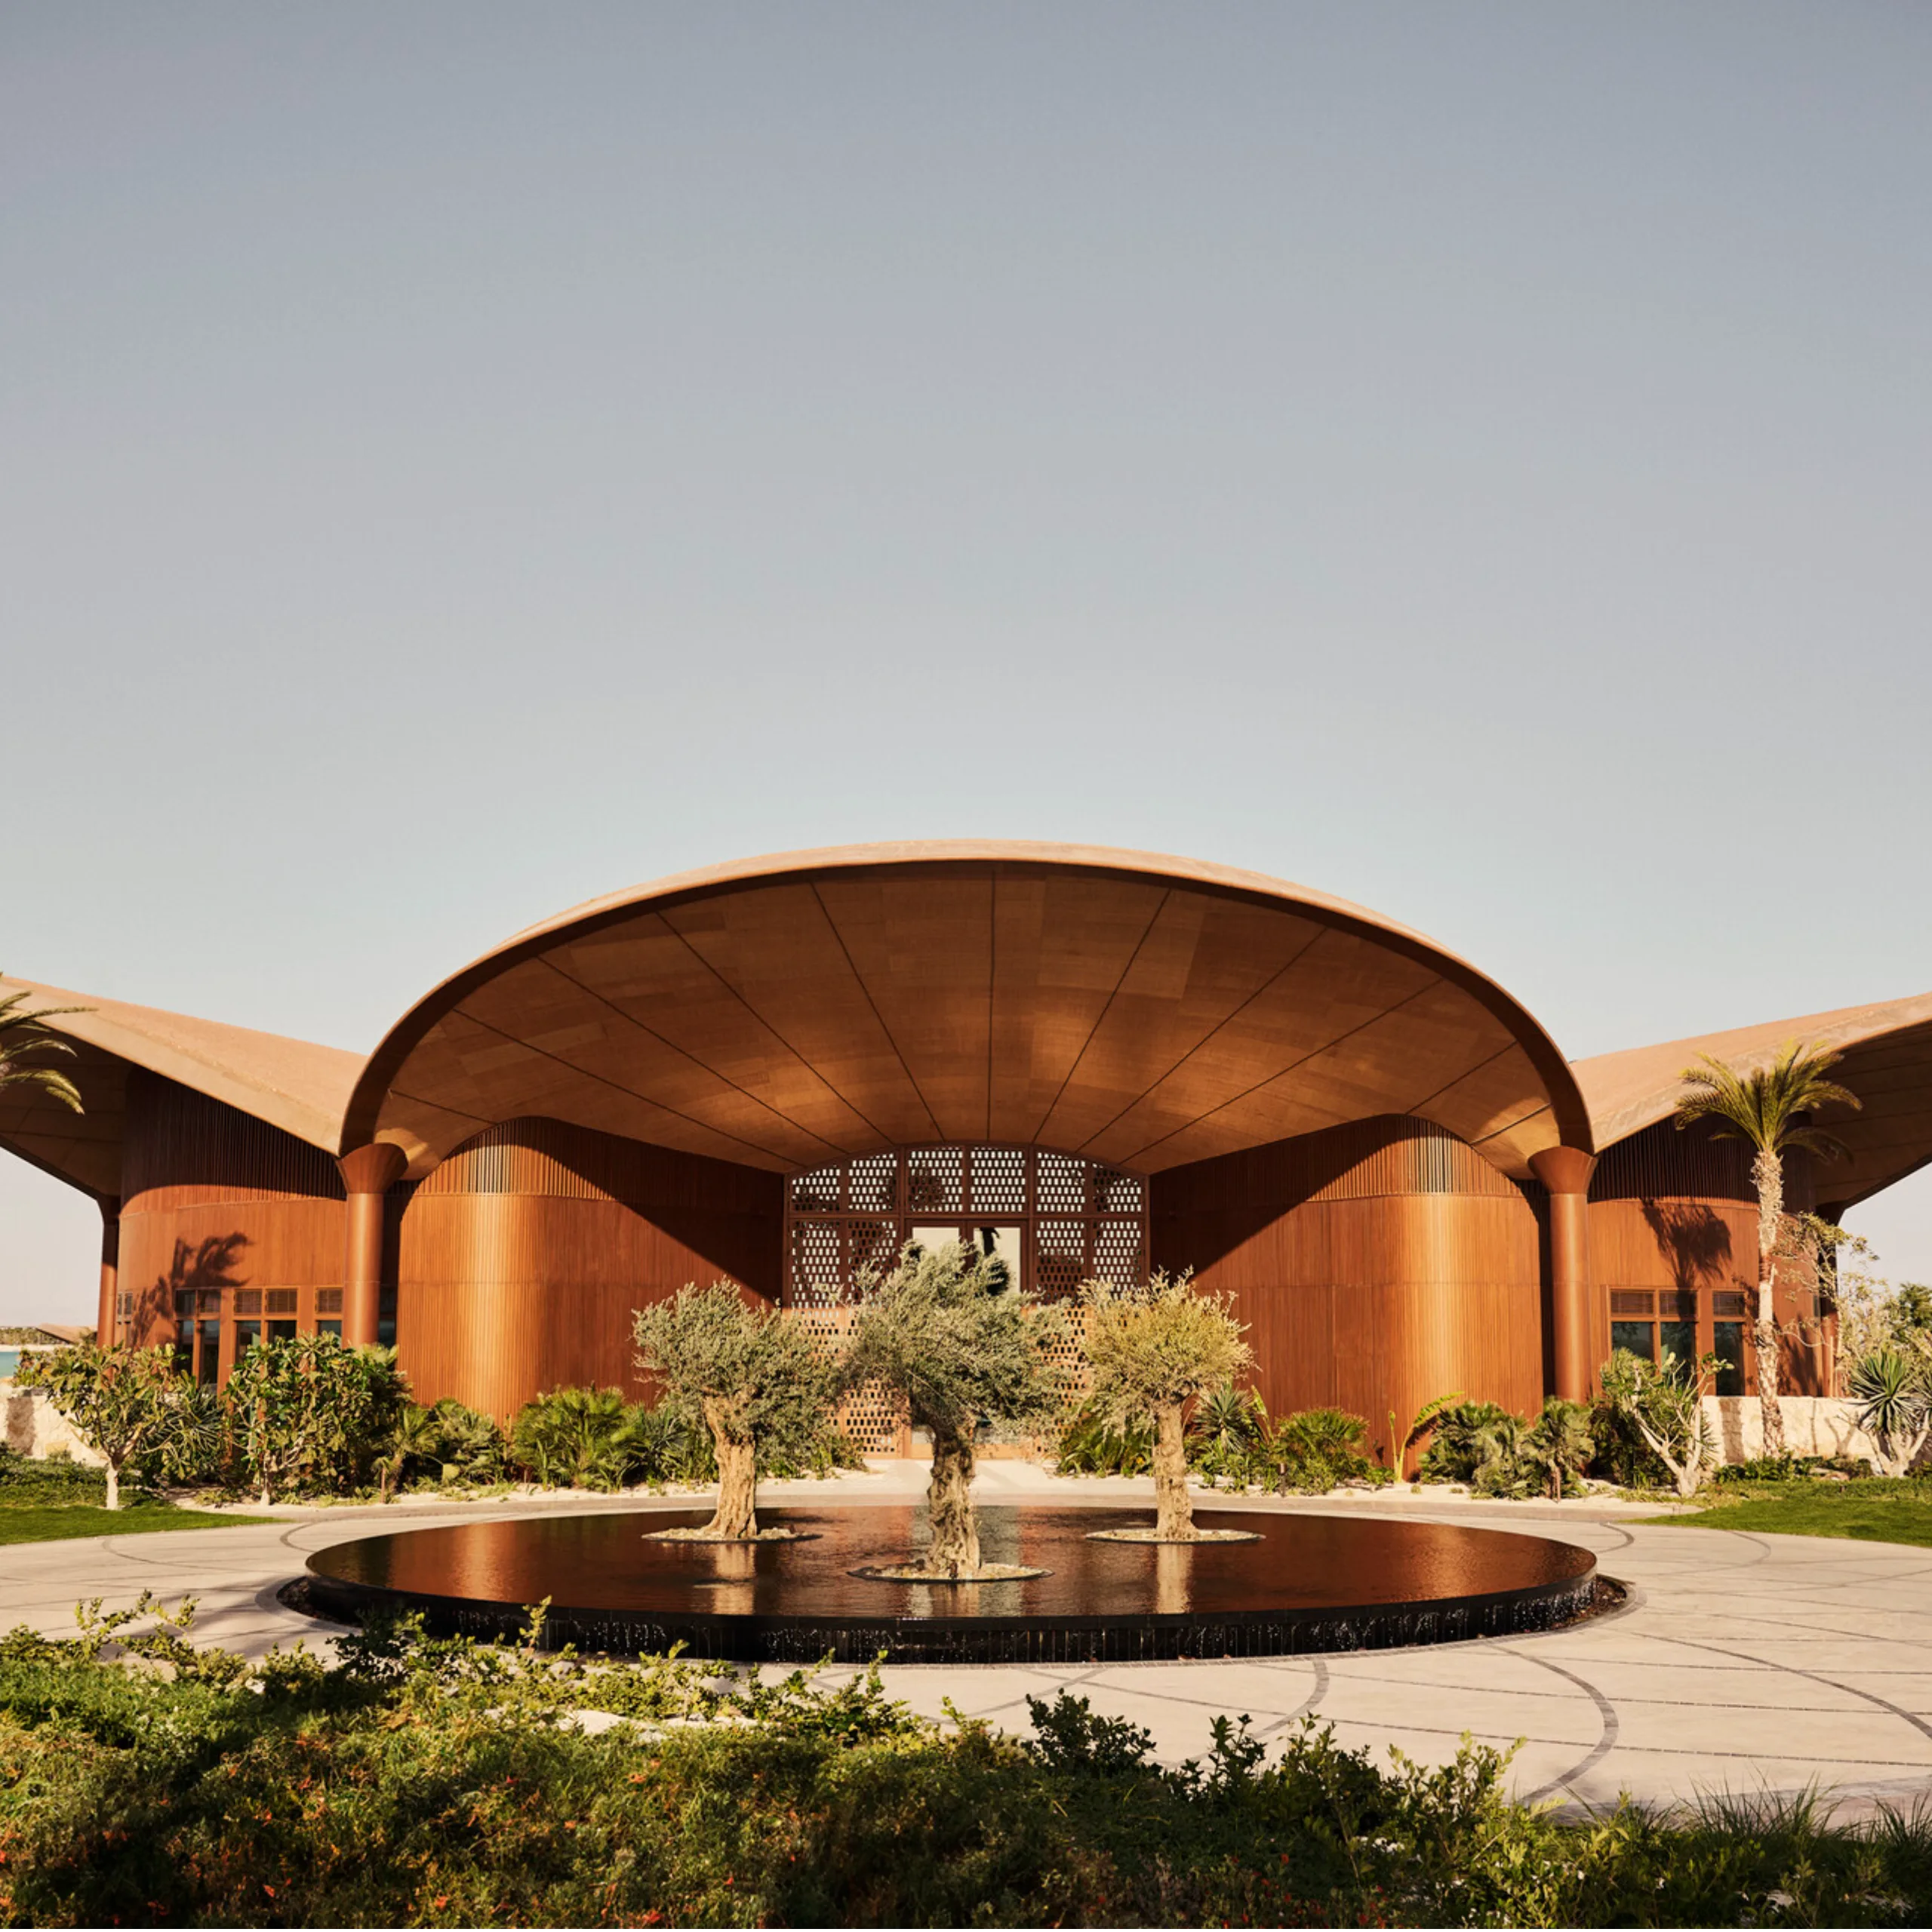
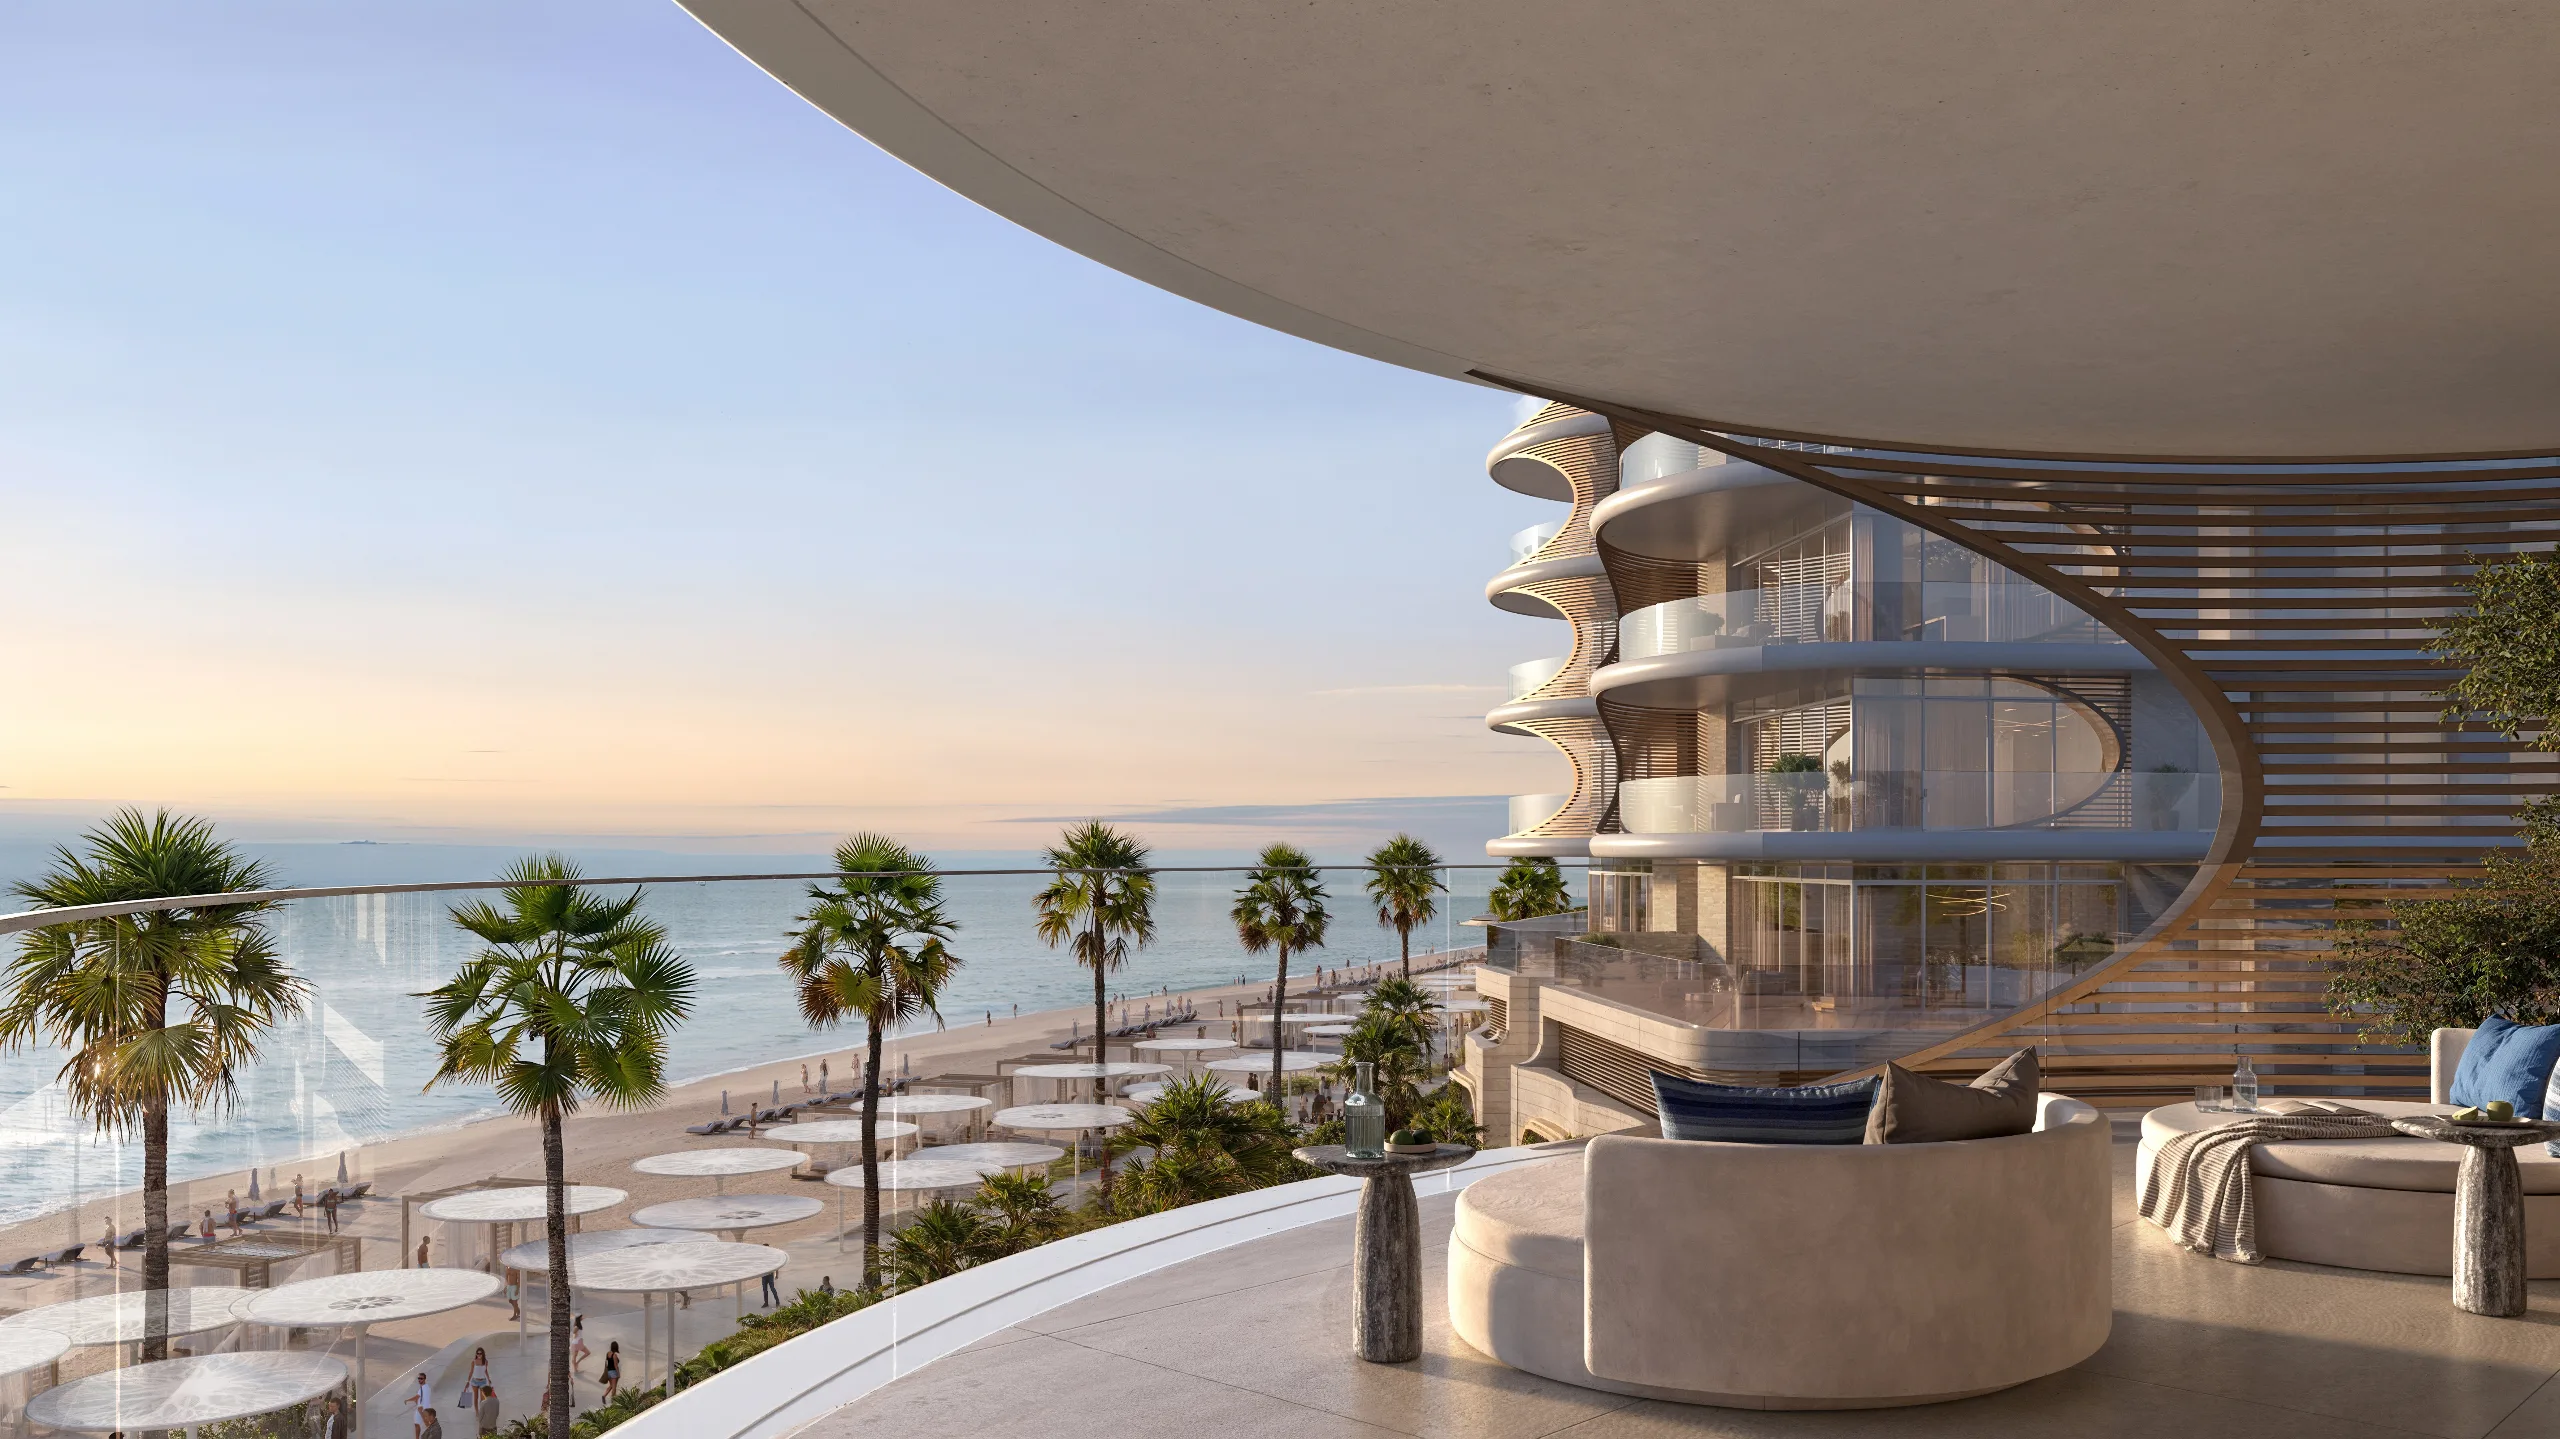
This year’s survey highlights the growing reach of branded residences, with an increasing share of development taking place outside cities in coastal and ski resort markets.

This year’s survey highlights the growing reach of branded residences, with an increasing share of development taking place outside cities in coastal and ski resort markets.
We assessed more than 200 brands across 90 countries, covering nearly 1,800 live and pipeline schemes.
While still modest in scale relative to the wider housing market, branded residences continue to exert a sizeable influence on luxury residential development.
The sector has helped set new benchmarks in hospitality-led services, wellness-focused amenities and lifestyle-oriented placemaking, some of which have influenced the broader prime residential market.
The influence of branded residences has been reinforced by a prolonged period of growth, with both project numbers and unit counts increasing sharply over the past decade. Since 2015, the number of global projects has almost tripled, increasing from 354 schemes to 903 by the end of 2025.
Current projections suggest the market will surpass 1,000 schemes this year, reaching approximately 1,088 developments globally by year end.
If realised, this would represent a total scheme count increase of around a fifth compared with 2025, extending the sector’s recent period of rapid development.
Industry participants have also disclosed around 200 pipeline projects for which scheme-level details were unavailable, suggesting the total market could move towards 2,000 schemes over the next five to 10 years.
Geographically, the market continues to be shaped by two dominant forces: the US and the Middle East. The US retains the largest concentration of operational stock. However, the Middle East is the sector’s most significant growth engine, and Dubai remains the world’s leading city market for branded residences.
Spain continues to stand out as one of the sector’s most dynamic growth markets and is the highest ranked European country for pipeline development.
While Madrid strengthens its position as an urban branded residence destination, lifestyle-led locations such as Marbella and the Costa del Sol continue to attract developers and buyers.
In 2016, fewer than four in 10 branded residence schemes were located outside major cities. Today, more than half are in coastal, island or mountain destinations, and the pipeline suggests this share will increase over the coming years.
The market is becoming increasingly diverse, with a rise in non-hotel names.
Hotel brands account for around 70% of operational schemes globally, but their share falls to 60% when pipeline developments are included, highlighting the growing influence of non-hotel players.
While hospitality operators remain the backbone of the sector, a widening range of fashion, automotive and lifestyle brands are establishing a presence. This broadening brand mix is creating a more competitive marketplace and giving developers new ways to differentiate projects and attract increasingly sophisticated buyers.
Liam Bailey is Global Head of Knight Frank’s Research Department, leading the firm’s global research strategy and overseeing projects across the UK and international markets.
Our global Branded Residential Developments team offers seamless sales, marketing, distribution, and consultancy solutions. Fill in your details and we'll be in touch to discuss your needs.
Delve deeper into the insights, access our comprehensive dataset, and explore future predictions from our team of experts.
Sorry!
An unexpected error has occurred.
Please try again later.